Retiring? Here’s what you can do with your super
After years of working and contributing to super, retirement is when you finally get to start using it.
But how should you access your super? Should you leave it invested, set up regular income payments or withdraw a lump sum?
There isn’t one answer that works for everyone. Your options depend on your age, whether you meet the conditions to access your super, how much you have saved and the lifestyle you want in retirement.
The good news is you generally have several options, and you can often combine them.
Here’s what to know before making a decision.
When can you access your super?
Retiring from work doesn’t automatically mean you can access your super. You need to meet the relevant conditions of release.
For many Australians, this may happen when they reach age 60 and cease an employment arrangement, or retire after reaching preservation age. You can generally access your super once you turn 65, even if you’re still working.
There are specific rules around what counts as retirement and how different conditions apply, so check your eligibility before making plans around your super balance.
TIP: If retirement is a few years away, start by checking when you can access your super and what your fund requires. You don’t want to build your retirement budget around money you can’t access yet.
Option 1: Leave your super invested in accumulation phase
You don’t have to move your super into an income stream as soon as you retire. You can leave it invested in accumulation phase, provided you meet your fund’s requirements.
However, investment earnings in accumulation phase are generally still taxed. The tax rate is generally up to 15%, with capital gains on assets held for at least 12 months generally taxed at an effective rate of up to 10%.
This is different from a retirement-phase income stream, where investment earnings can be tax-free, subject to the relevant rules and limits.
Leaving your money in accumulation might suit you if you don’t need regular income from your super straight away. But it’s worth comparing the tax treatment, fees, investment options and your longer-term retirement plans before deciding.
TIP: Don’t assume leaving your super where it is will automatically be the most tax-effective option. Compare accumulation with a retirement income stream and consider getting advice about what suits your circumstances.
Option 2: Set up a retirement income stream
When you retire, you may be able to move some of your super from accumulation phase into a retirement income stream. This allows you to draw regular payments from your super to help cover your living costs.
There are different types of retirement income streams, but one of the most common is an account-based pension. You transfer eligible super savings into an account-based pension and receive regular payments while the remaining balance stays invested.
Your money can continue to earn investment returns, although its value can also fall. You’ll need to draw at least the minimum amount required each financial year, based on your age and account balance.
There’s also a limit on how much super you can transfer into retirement phase. This is known as the transfer balance cap.
The general transfer balance cap is $2.1 million from 1 July 2026. Your personal cap may be lower, depending on whether you’ve previously started a retirement income stream and how much of your cap you’ve already used. The cap applies across your retirement-phase income streams, not separately to each account.
You can generally leave any amount above your available cap in accumulation phase, where investment earnings continue to be taxed under the usual super rules.
TIP: Before setting up an income stream, consider how much income you need, how you want your super invested and how much of your transfer balance cap you have available. You can check your personal cap through your ATO account linked to myGov.
Option 3: Withdraw a lump sum
You may be able to withdraw some or all of your super as a lump sum once you meet the relevant access rules.
Some retirees use a lump sum to pay off a mortgage, clear other debts, renovate their home or cover a large expense.
Having access to a large amount of cash can feel reassuring, but it’s worth thinking carefully about what happens next.
Once the money leaves super, you’ll need to decide where to keep or invest it. You may also lose some of the tax advantages that can apply to money held within super, depending on how the money is used and your circumstances.
What you do with the withdrawn money can affect how it’s assessed for government benefits, including the Age Pension. Super is generally already assessed under the Age Pension means tests once you reach Age Pension age, so taking a lump sum does not, by itself, necessarily change your entitlement. Services Australia explains how it assesses super and withdrawals.
TIP: Before taking a large lump sum, work out exactly what you need the money for. Compare the benefits of withdrawing it with the impact on your remaining retirement savings and future income.
Option 4: Combine your options
You don’t have to choose just one approach.
For example, you might keep some money invested in accumulation phase, use part of your balance to start an account-based pension and withdraw a smaller lump sum for a specific expense.
This can give you a mix of regular income and access to cash when you need it.
The right balance depends on your spending needs, other assets, investment preferences and how long your savings may need to last.
It’s also important to consider how much money you want to keep available for unexpected costs, such as home repairs or medical and care expenses.
TIP: Think about your super as part of your overall retirement plan, rather than making decisions about each account in isolation. Include your savings, investments, property and any expected government benefits.
How is super taxed after retirement?
For many Australians, super withdrawals are generally tax-free from age 60 when paid from a taxed super fund, provided the relevant conditions are met.
However, tax treatment can differ depending on your age, the type of super benefit, whether it contains an untaxed component and how you access the money.
Your decision may also affect tax outside super. For example, interest or investment income earned after withdrawing money can have different tax consequences from earnings within super.
The rules around contributions, income streams and retirement-phase limits can also matter when setting up your retirement income.
TIP: Don’t choose a withdrawal strategy based on tax alone. Consider your cash flow, investment strategy, government benefits and longer-term retirement needs as well.
How do you make your super last?
One of the biggest questions in retirement is how much you can safely spend.
You want to enjoy the money you’ve worked hard to save, but you also need to make sure it can support you for as long as you need it.
There are a few things worth considering.
Work out your annual spending
Separate essential expenses, such as housing, food, utilities and insurance, from discretionary spending, such as holidays, hobbies and dining out.
This gives you a clearer idea of the income you need and where you may have flexibility.
Consider all your income sources
Your super is only one part of your retirement finances. You may also have savings, investments, rental income, employment income or an entitlement to the Age Pension.
Look at these together to understand how much money you have available.
Review your investment strategy
Retirement doesn’t mean you should automatically move everything into cash. Your savings may need to remain invested for decades, so inflation and investment risk still matter.
Your strategy should reflect your circumstances, timeframe and tolerance for risk.
Review your plan regularly
Your spending and circumstances will change over time. Review your budget, income and investments regularly, and make adjustments when needed.
TIP: Use a retirement income calculator to test different scenarios. Consider what happens if you spend more than expected, investment returns are lower or you live longer than planned.
Check your super with Rask
Before deciding how to access your super, make sure you understand what you have.
Check your balance, investments, fees, insurance and beneficiaries. These are the basics, but they can make a real difference to how well prepared you are for retirement.
The Rask Super Checker lets you explore an indicative retirement projection using your current balance and assumptions. Check your fund directly for details such as fees, insurance and beneficiaries.
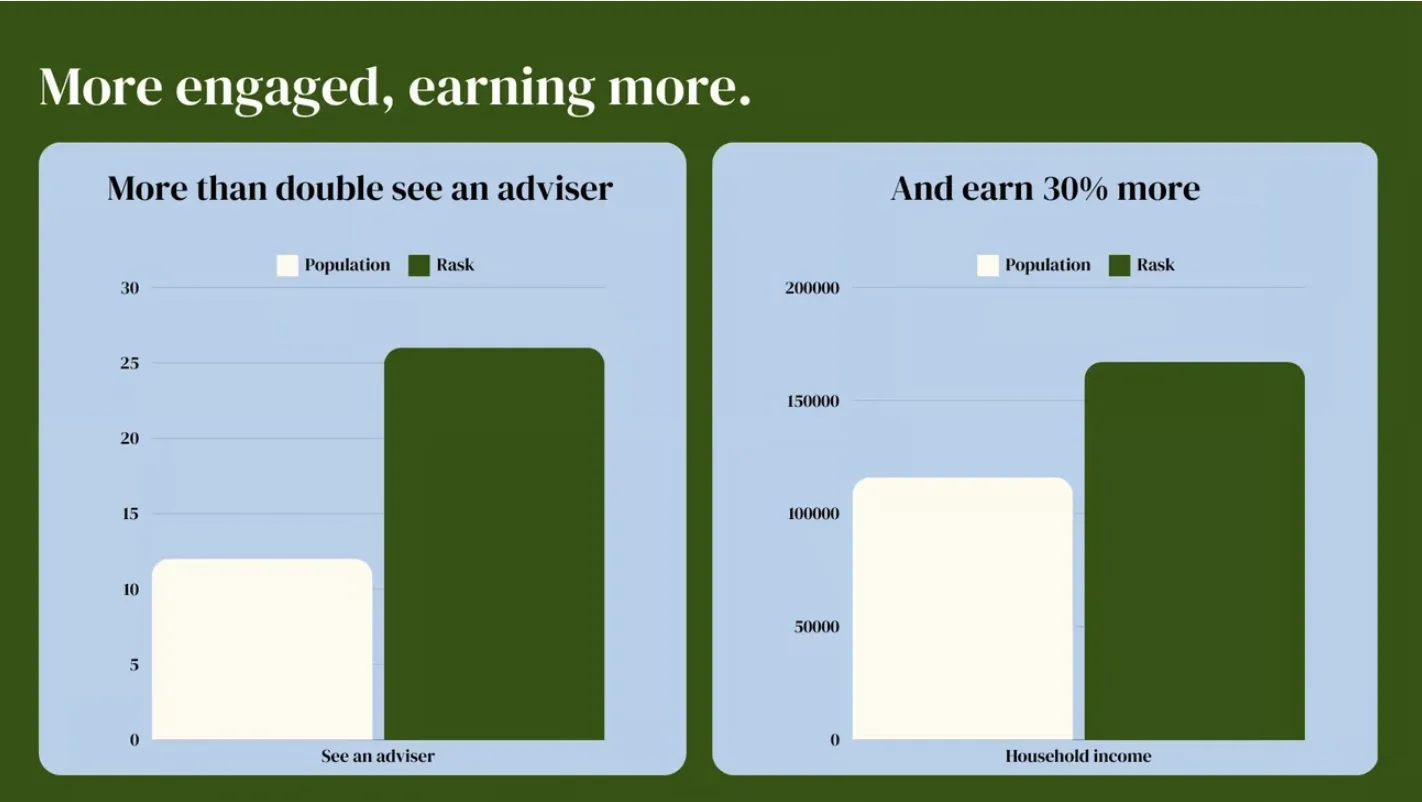
If you’re approaching retirement or already retired and want help understanding your options, Rask Financial Advice can help you explore how your super fits into your broader financial situation.
Explore Rask Financial Advice.
The goal isn’t simply to work out how to access your super. It’s to work out how to use it to support the retirement you want.
This article contains general financial information only and does not take into account your objectives, financial situation or needs. Consider your own circumstances and seek personal advice before acting on anything discussed.