What actually happens to your super when you retire?
Try our free wealth checker tool
It sounds like there should be a giant red button that says “retirement mode” — but, as usual with super, it’s a little more paperwork-y than that.
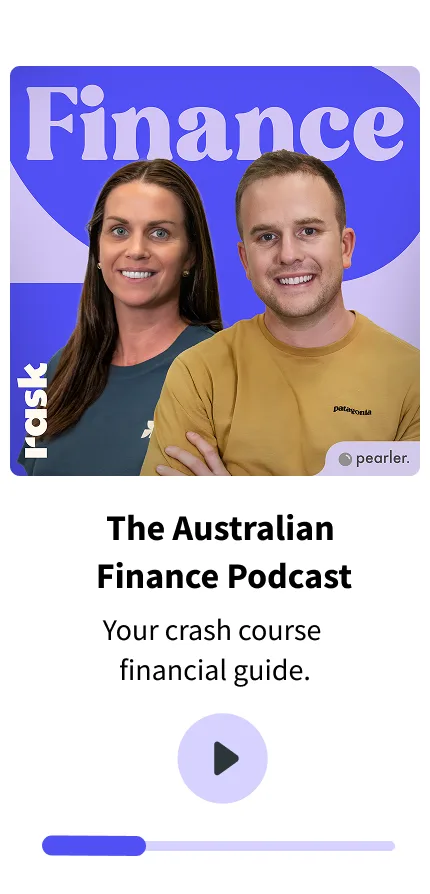
In this episode of the Australian Finance Podcast, also shared on the Australian Retirement Podcast, Owen is joined by Tahli Cavagnino, Senior Financial Adviser and co-head of financial advice at Rask Advice, to unpack what happens to your super as you move towards retirement.
General advice warning: This episode contains general information and general advice only. Please consider your own circumstances and seek professional advice before making financial decisions.
We cover when you can generally access your super, what “pension mode” actually means, how super can be taxed before and after retirement, and some of the big trade-offs people face as they approach retirement.
Plus, we answer listener questions on indexed versus active high growth super options, whether people typically change funds when moving into pension phase, and whether you still need an emergency fund once you can access your super.
In this episode
- Owen’s news of the week: why you shouldn’t rush changing super funds
- The importance of reading the PDS/TMD and checking the AFSL before acting
- When Australians can generally access their super
- What it means to turn your super into “pension mode”
- Is it a button, a form, a phone call — or all of the above?
- A simple overview of tax on super before and after retirement
- Why defined benefit funds can be different
- Minimum pension drawdown rates explained
- Do most people withdraw only the minimum from super?
- The retirement mortgage question: super versus debt
- Super versus investing outside super if you want to retire before 60
- Indexed high growth versus active high growth super options
- Whether different super funds suit different life stages
- Whether you still need an emergency fund once super is accessible
Listener questions
- Hot Takes: “For a long-term investor choosing a high growth option inside super, what should they think about when comparing indexed high growth and active high growth managed by the super fund?”
- Barren Jo: “You’ve mentioned that different style super funds may suit people at different stages. Can you explain this more? Do people typically change super funds when switching to pension mode, and if so, why?”
- WannabeWhale: “Is an emergency fund necessary when you have access to your super?”