Private credit has moved from an institutional niche into the portfolios of everyday investors seeking income and lower volatility. But higher income is not free: investors are paid to accept illiquidity, manager risk and the possibility that redemptions are limited when everyone wants out at once.
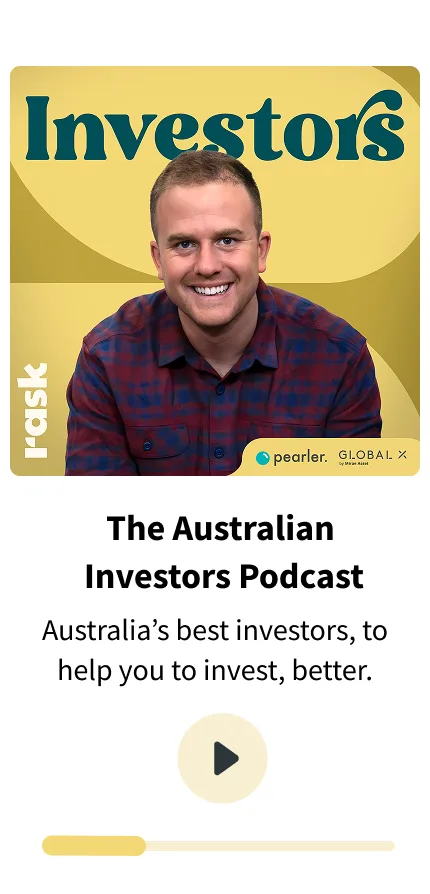
In this episode of the Australian Investors Podcast, Owen Rask sits down with Nehemiah Richardson, CEO of Pengana Credit, to unpack how corporate private credit works and what investors should understand before committing their money.
Nehemiah explains why manager selection matters when loans cannot be traded every day, how diversification across managers, industries, geographies and lending strategies can reduce concentration risk, and why the liquidity terms should match the time you can genuinely leave your capital invested.
They examine the recent headlines around large US private credit funds, software exposure and redemption queues, including the difference between a genuine credit problem and a liquidity event. Nehemiah also compares Australia’s more concentrated private credit market — particularly its exposure to property and construction — with the broader opportunity set available in the US and Europe.
You’ll also hear how professional investors think about underwriting, covenants, capital protection, portfolio construction and recovery when a borrower runs into trouble. The central message is simple: understand the manager, understand the assets, understand the worst-case liquidity, and do not invest in anything that cannot be clearly explained.